
01 / Simply Sold
A clear place to start
Neither option should be chosen from a promise about a guaranteed credit outcome or a fixed timeline. Talk with your mortgage servicer, a housing counselor, and a Kentucky attorney about your actual loan and deadlines.
02 / Simply Sold
What makes a short sale different?
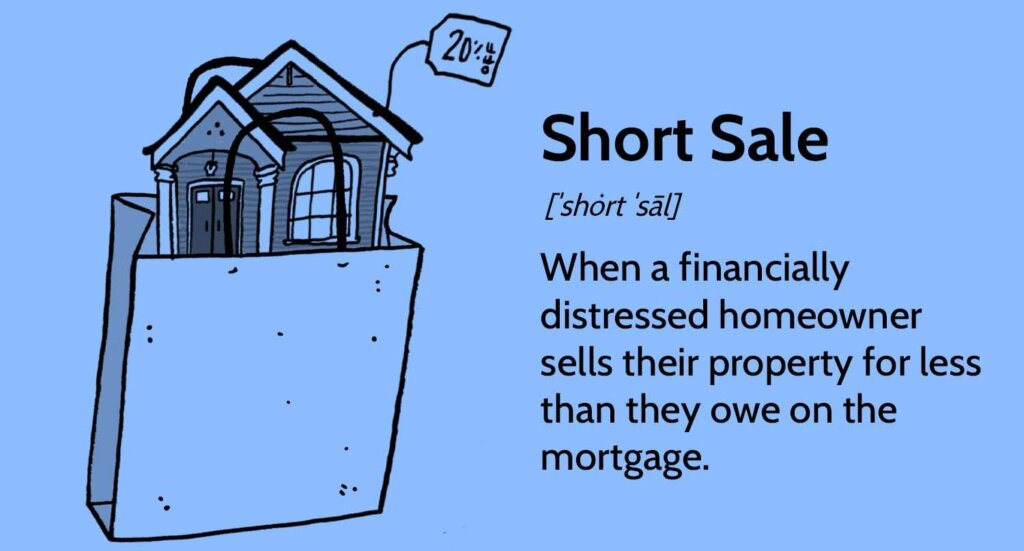
The CFPB explains short sales as an option involving a sale for less than the amount owed on the mortgage. Approval and the treatment of any unpaid balance matter. A purchase offer alone is not the lender’s approval.
Ask the servicer what application and supporting documents it requires. Before accepting terms, have your attorney review whether the remaining debt is released or could still be collected. A tax professional can explain potential tax consequences.
03 / Simply Sold
What happens in a Kentucky foreclosure?
The case and court orders determine the process and the relevant deadlines. Kentucky’s master commissioners assist with judicial sales, including foreclosure sales.
If you receive court papers or a scheduled sale notice, seek legal advice promptly. Contacting a buyer, requesting counseling, or signing an offer should not be treated as confirmation that the proceeding has stopped.
04 / Simply Sold
Compare the decisions that matter
Who approves the transaction? A short sale requires the necessary creditor approvals. In a foreclosure, the legal proceeding and court orders govern enforcement and sale.
How long will it take? Lender review, title issues, court requirements, and buyer conditions can affect the schedule. There is no universal number of days that makes one option available for every homeowner.
04 / Simply Sold
What happens to the remaining debt? Ask about any unpaid mortgage balance, other liens, and the written terms of a release. Do not assume a sale or foreclosure automatically erases every obligation.
Sell The Simple Way. Get Started Now…
What happens to credit and taxes? Both can have significant consequences, and the details differ by borrower and transaction. Avoid promises about a specific score change, recovery period, or future loan eligibility.
05 / Simply Sold
Consider alternatives before committing
If keeping the home is your goal, ask the servicer and a HUD-approved housing counselor about assistance. If the property’s value can cover the required debt and sale costs, an ordinary sale may be another option. The CFPB mortgage-help page is a useful starting point for counseling resources.
For the sale process, read our guide to selling a house in foreclosure in Kentucky.
06 / Simply Sold
Where a cash offer fits
Sell The Simple Way. Get Started Now…
Simply Sold can evaluate an as-is purchase. A cash buyer may remove the need for buyer mortgage financing, but that does not eliminate title requirements, creditor approvals, or court deadlines.
Tell us whether a short sale or foreclosure case is involved before we discuss timing. If we can make an offer, compare its written terms with your other options and have your attorney review the requirements.
Request a no-obligation cash offer or contact us to talk about the property.
About: Beau Hollis
Beau Hollis is the founder of Simply Sold, a Louisville-based home-buying company. He writes about property condition, seller decisions, and the direct home-sale process. Legal, insurance, and tax questions should be reviewed with the appropriate professional.
Your next step can be simple
Let’s talk about your house.
Tell us about the property and the timeline you have in mind. We’ll explain a direct purchase so you can decide whether it fits.
Request a cash offer